


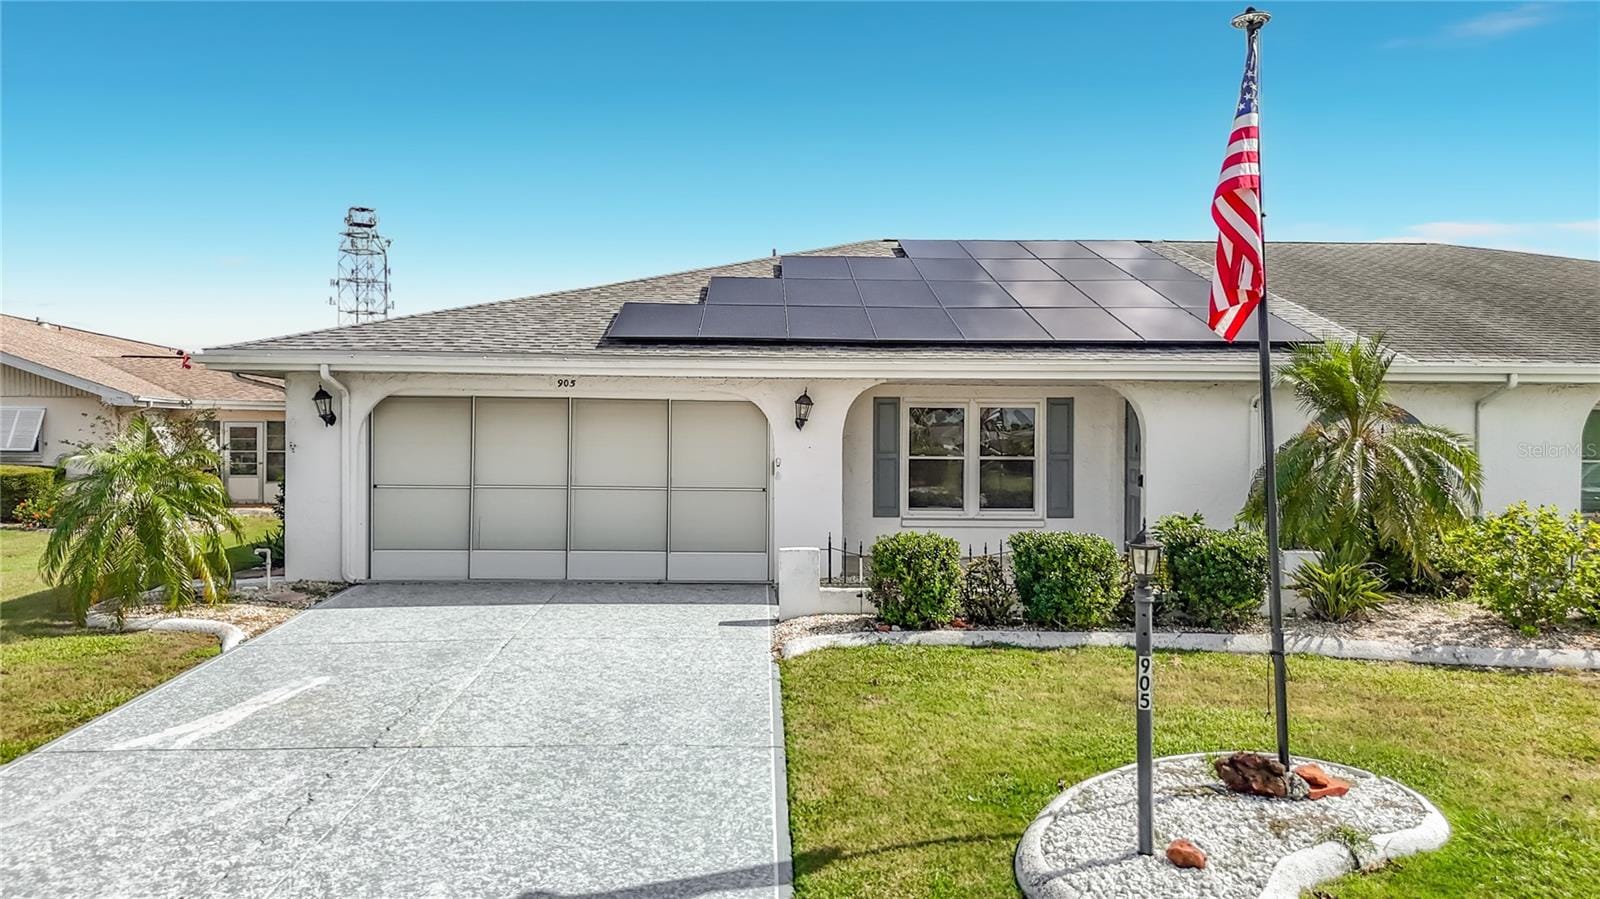
- New
$255,000
2 bd · 2 ba · 1,516 sq ft
905 BLUEWATER DRIVE, Sun City Center 33573
Listing courtesy of CHARLES RUTENBERG REALTY INC

First-time buyers · Your first acquisition
The same care the house brings to every acquisition, from the very first. Here is the whole path from budget to keys, in plain language, with tools to test the numbers and a broker to answer the questions in between.
What matters to you
Tell us what you love, and we'll sort these around you
Four easy questions, about a minute. Every home will tell you why it made your list.
The path
Affordability
An estimate based on your income, debts, and the costs of owning. For planning only, not a loan offer.
Car, student loans, card minimums
Sets the property tax estimate. Florida taxes reset at sale.
Get real quotes; flood coverage is separate.
Inspired Nooks Realty
Affordability calculator
Estimated comfortable range
$245,000 to $270,000
Get an exact estimate from the Pinellas County Property Appraiser, or run a QReport: property background check on the address (permits, system ages, flood and new-owner taxes on one page; an independent service).
The rule we used
Comfortable: housing costs up to 28% of gross monthly income, and housing plus other debts up to 36%. Upper: 31% and 43%. Housing includes principal, interest, taxes, insurance, and HOA on a 30-year loan. We solve for the price where the lower of the two limits is met. Property taxes follow the Pinellas County Property Appraiser's new-owner method: 85% of the price, less the Florida homestead exemption, at last year's rates for the area, without special assessments.
An estimate for planning only, not a loan offer or pre-approval. Mortgage insurance, closing costs, and lender requirements are not included and vary by loan type.
Next, just out of curiosity: what would closing cost at that price?
Rent vs. buy
It often depends on how long you stay. Change the years and watch the answer move.
Nobody knows this. Try a few.
Inspired Nooks Realty
Rent or buy?
Over 7 years, estimated
Renting may cost about $6,349 less.
Assumes about 3% buying costs and 7% selling costs, a 30-year fixed loan, and no mortgage insurance or income-tax effects. Net cost of owning is what you pay in, plus the return your down payment could have earned, minus what you keep at sale. An estimate for planning only, not a loan offer or financial advice.
Down payment help
State, county, and city programs sometimes help first-time buyers with down payment or closing costs. Eligibility, amounts, and terms change often and usually depend on income, price limits, and the lender you use.
Ask us which state and county programs you may qualify for, and we will point you to lenders who work with them.
Trusted Partners · When you make an offer
 Matt KeelinCapital City Home Loans
Preferred Lender · NMLS 2592584
Pre-approvals, purchase and refinance loans across Tampa Bay, with clear numbers and fast answers.
Meet MattMatt Keelin is married to our broker-owner, Cara Savell Keelin. You are free to choose any lender. Disclosure
Home, auto, flood, and commercial insurance quotes for Florida properties.
Get an insurance quote (opens in a new tab)Visit websiteTitle and escrow for your closing, with a closing cost calculator to see your numbers early.
Your contact is Alexandra Ashey: (727) 594-8159, alex@bluebricktitle.com. You are always free to choose any title company.
Estimate closing costs (opens in a new tab)Visit websiteFounding sponsor of CE at Sea, an event hosted by Inspired Nooks Realty. You may choose any provider. Disclosure
Home inspections scheduled around your offer and inspection period.
Schedule an inspection (opens in a new tab)Visit websiteFounding sponsor of CE at Sea, an event hosted by Inspired Nooks Realty. You may choose any provider. Disclosure
Repair and maintenance concierge for Tampa Bay homes.
Repairs before a sale, punch lists after an inspection, and upkeep once you are settled in, coordinated with local tradespeople.
Request a repair or maintenance visit (opens in a new tab)Tampa Bay Home Maintenance is a d/b/a of Inspired Nooks Realty, LLC. You are free to choose any provider. Disclosure
The background check for any house: permits, system ages, flood and new-owner taxes on one page.
Run a QReport (opens in a new tab)You're always free to choose any provider you like. These are the companies that have gone above and beyond for our clients, time and again.
First homes
$255,000
2 bd · 2 ba · 1,516 sq ft
Listing courtesy of CHARLES RUTENBERG REALTY INC
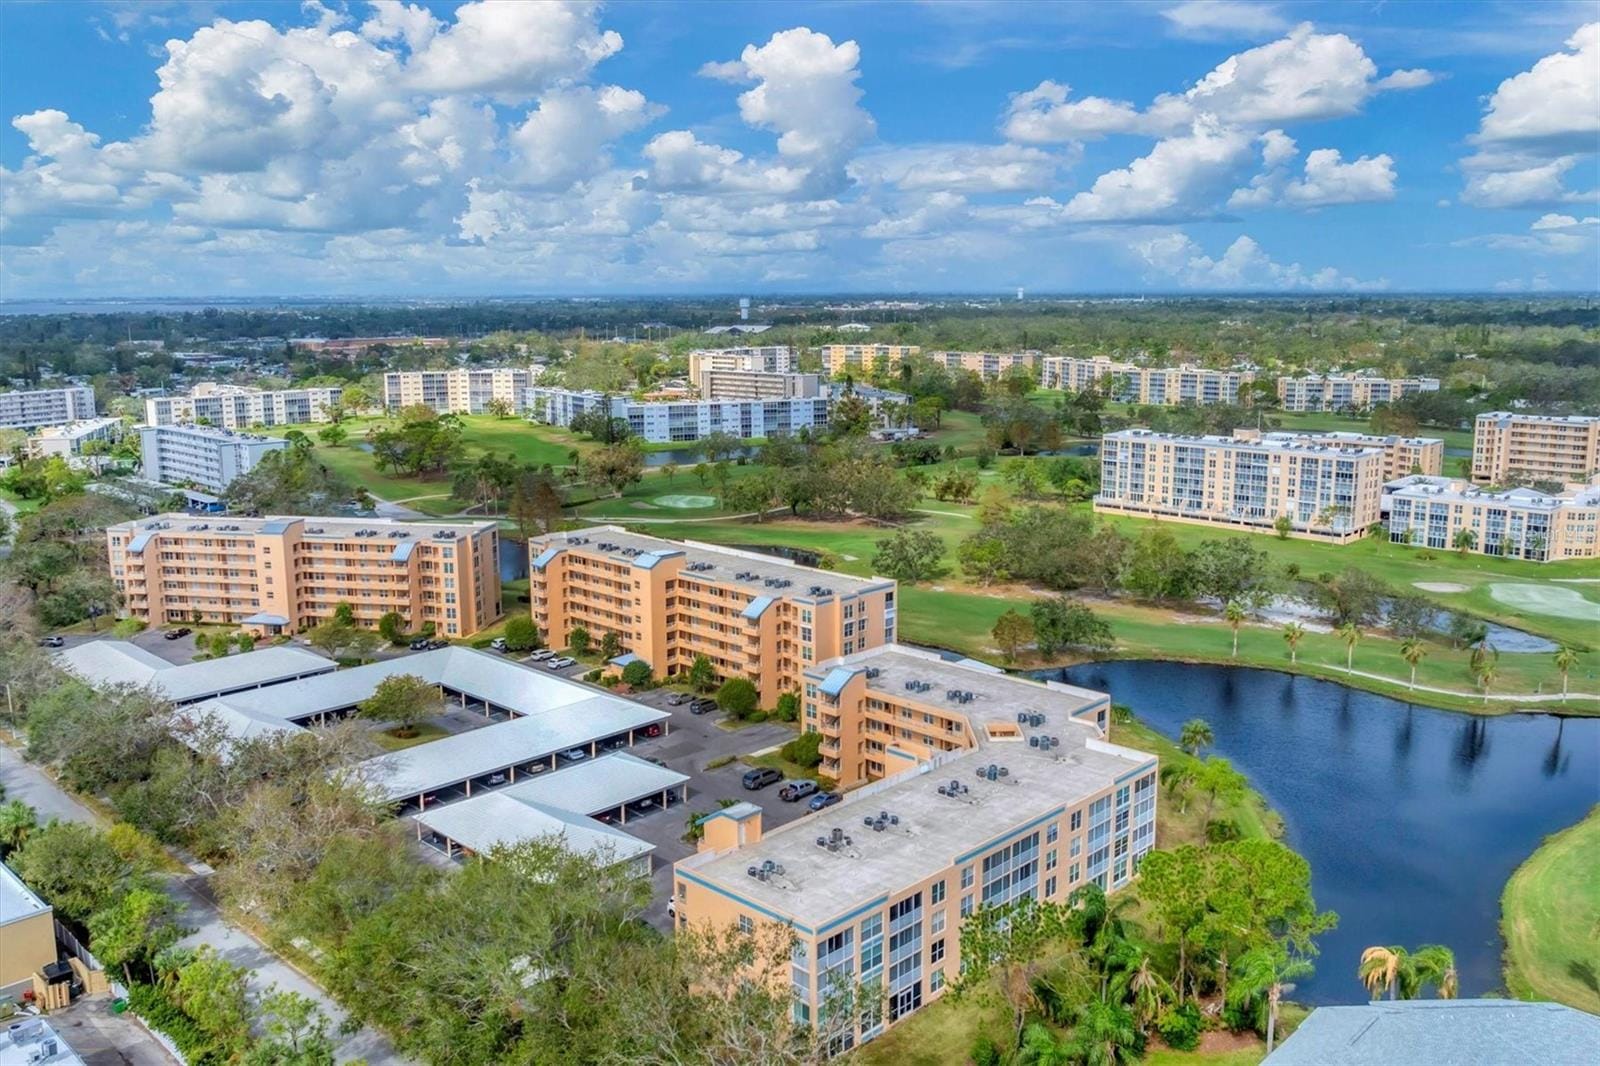
$265,000
2 bd · 2 ba · 1,256 sq ft
Listing courtesy of FINE PROPERTIES
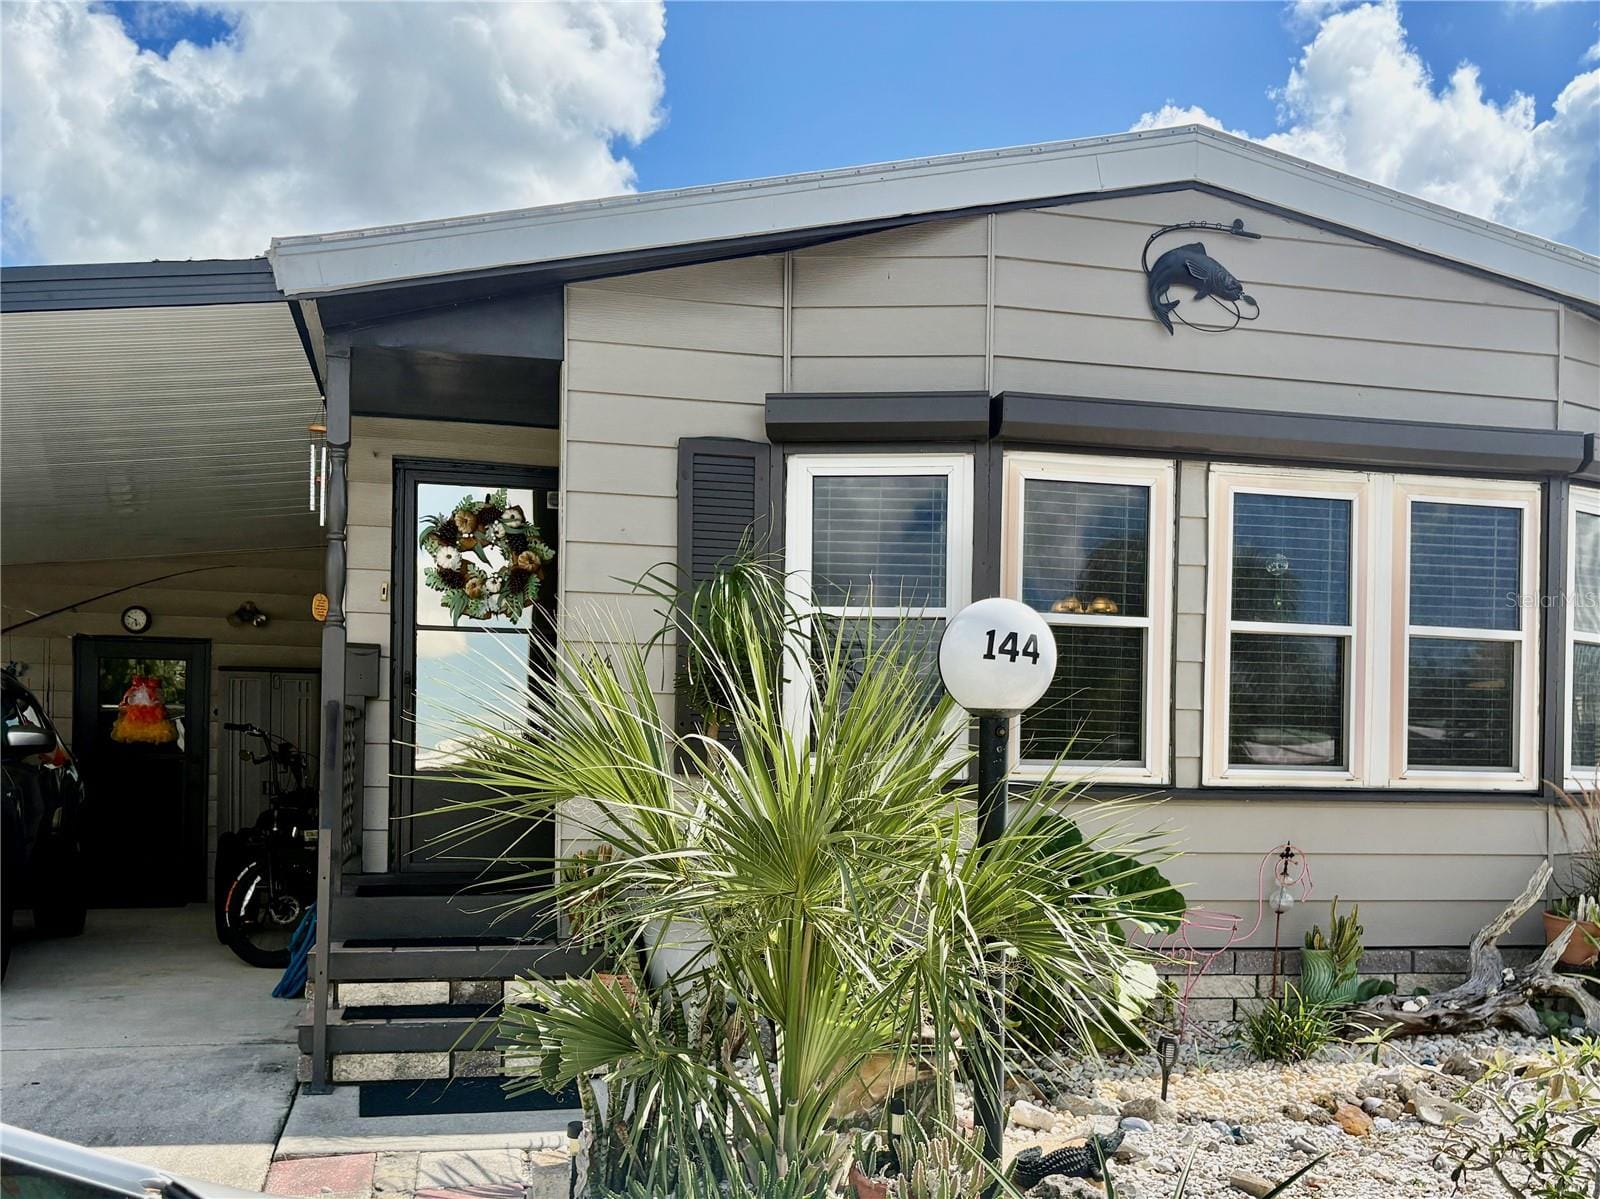
$210,000
2 bd · 2 ba · 1,336 sq ft
Listing courtesy of MS REALTY MICKEY SCHWEITZER & ASSOCIATES LLC
Questions
Private introductions · By appointment
Tell us where you are in the process. We will help you plan the next step, whether you are ready this month or next year.
Prefer to talk? Call (727) 342-0399
or write info@inspirednooksrealty.com.